Backtest the logic
Run a strategy against historical data with the selected instrument, range, and execution assumptions.
Backtest strategy logic, validate its behavior, and explore parameters before deciding what belongs in your trading workflow.
Historical and simulated results depend on data and execution assumptions and do not guarantee live performance.
Run a strategy against historical data with the selected instrument, range, and execution assumptions.
Use the Validator workflow to review results and investigate how the strategy behaves under the chosen test setup.
Use the Optimizer to compare parameter combinations and fitness results, then review robustness rather than selecting on one result alone.
Select a compiled strategy and record the market, history, parameters, and cost assumptions.
Inspect the backtest and validation results, and compare parameter sets when optimization fits the question.
Create a fresh strategy instance and observe it with LocalPaper before considering an external account.
Yes. Build it in Code Lab and use the supported strategy selectors and research workflow for your installed release.
No. Historical granularity, fill models, commissions, slippage behavior, and provider conditions affect the result. Record and review the assumptions for each run.
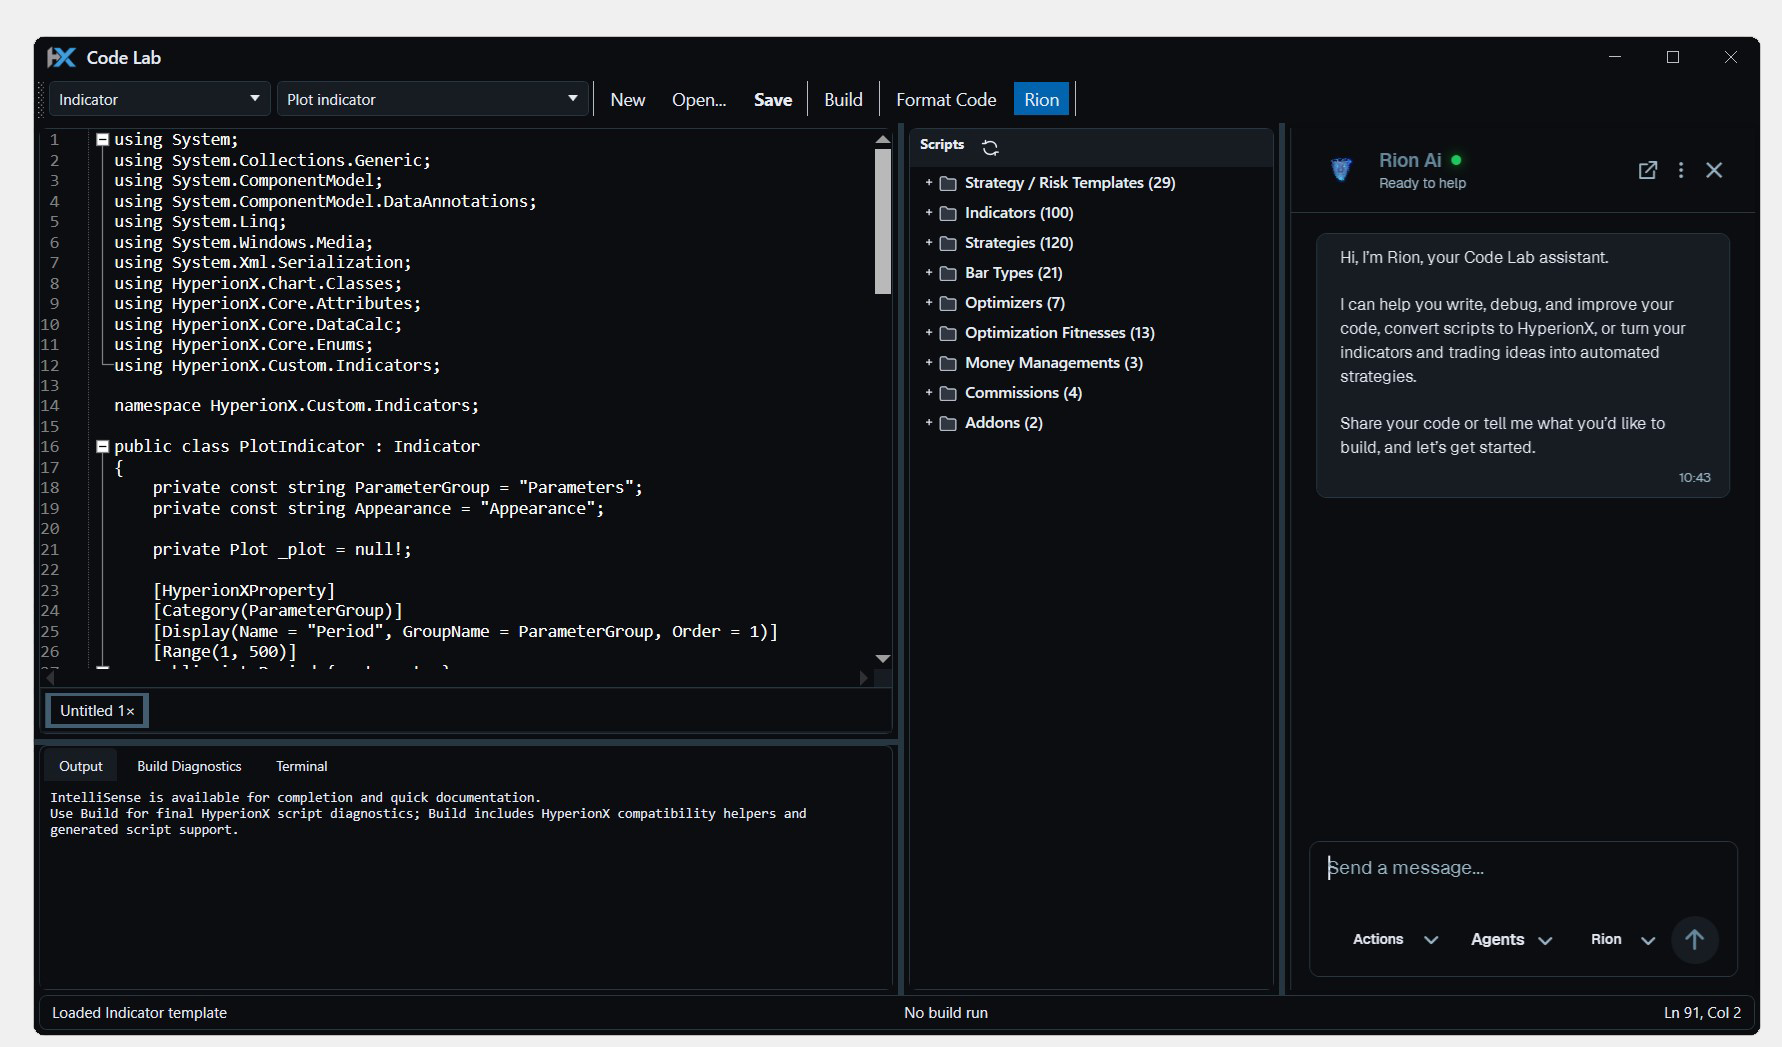
Write, compile, and test C# indicators and strategies inside HyperionX. Build custom tools where you already chart, research, and trade.
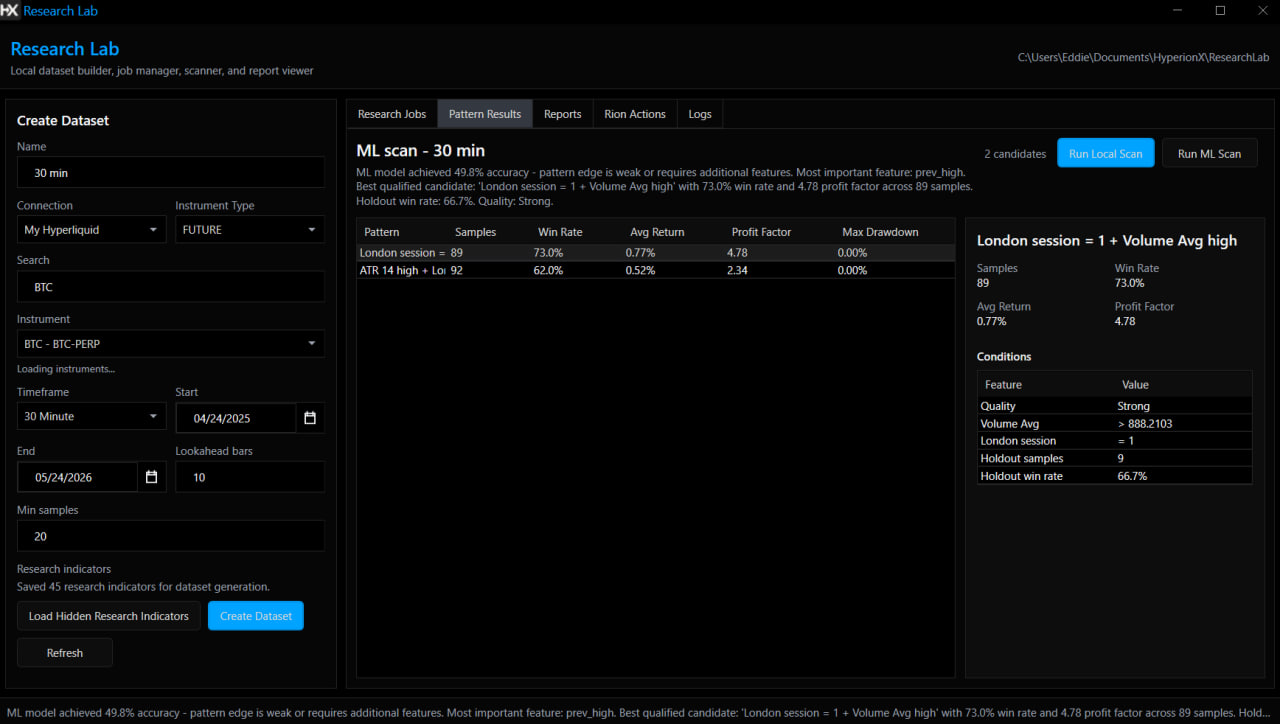
Explore Code LabBuild feature datasets, run supported research jobs, and compare reports inside the trading desktop. Keep your experiments close to the strategies they inform.
Explore Research Lab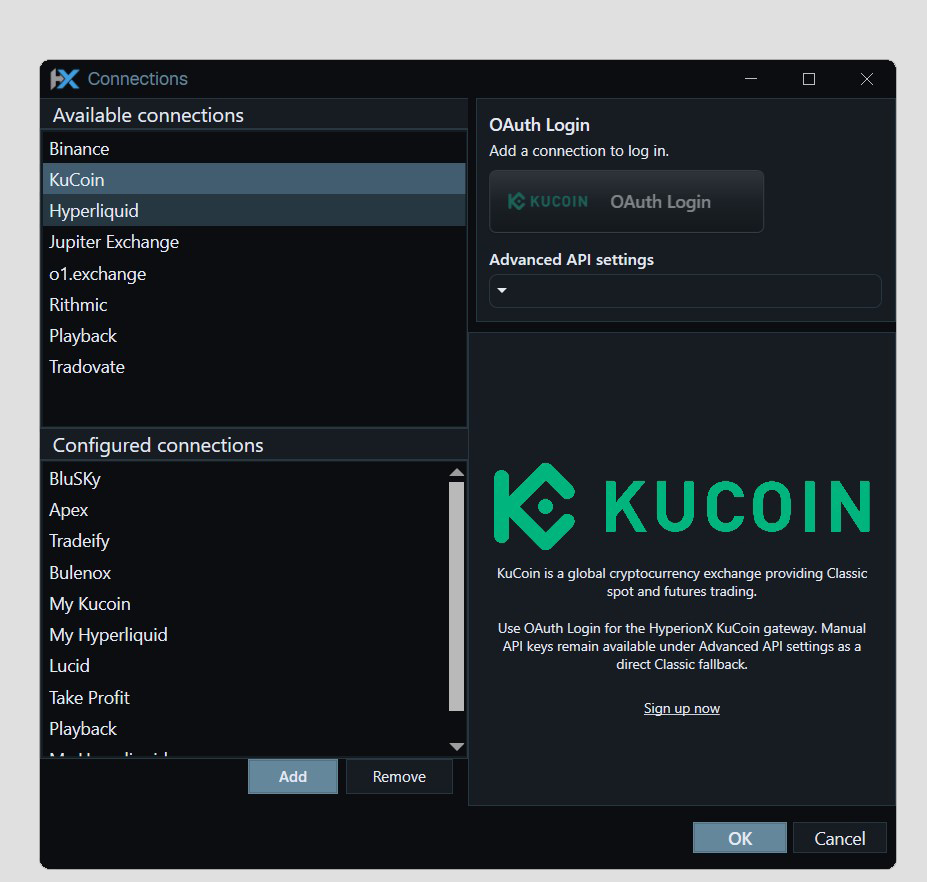
Bring supported futures and crypto data into HyperionX. Configure providers, inspect connection state, and choose the account for your workflow.
Explore ConnectionsCharts, code, research, and execution. Find your flow in one Windows desktop platform.
We use essential browser storage and, with your permission, optional analytics and CRM live chat. Visit our Cookie Policy for more info.